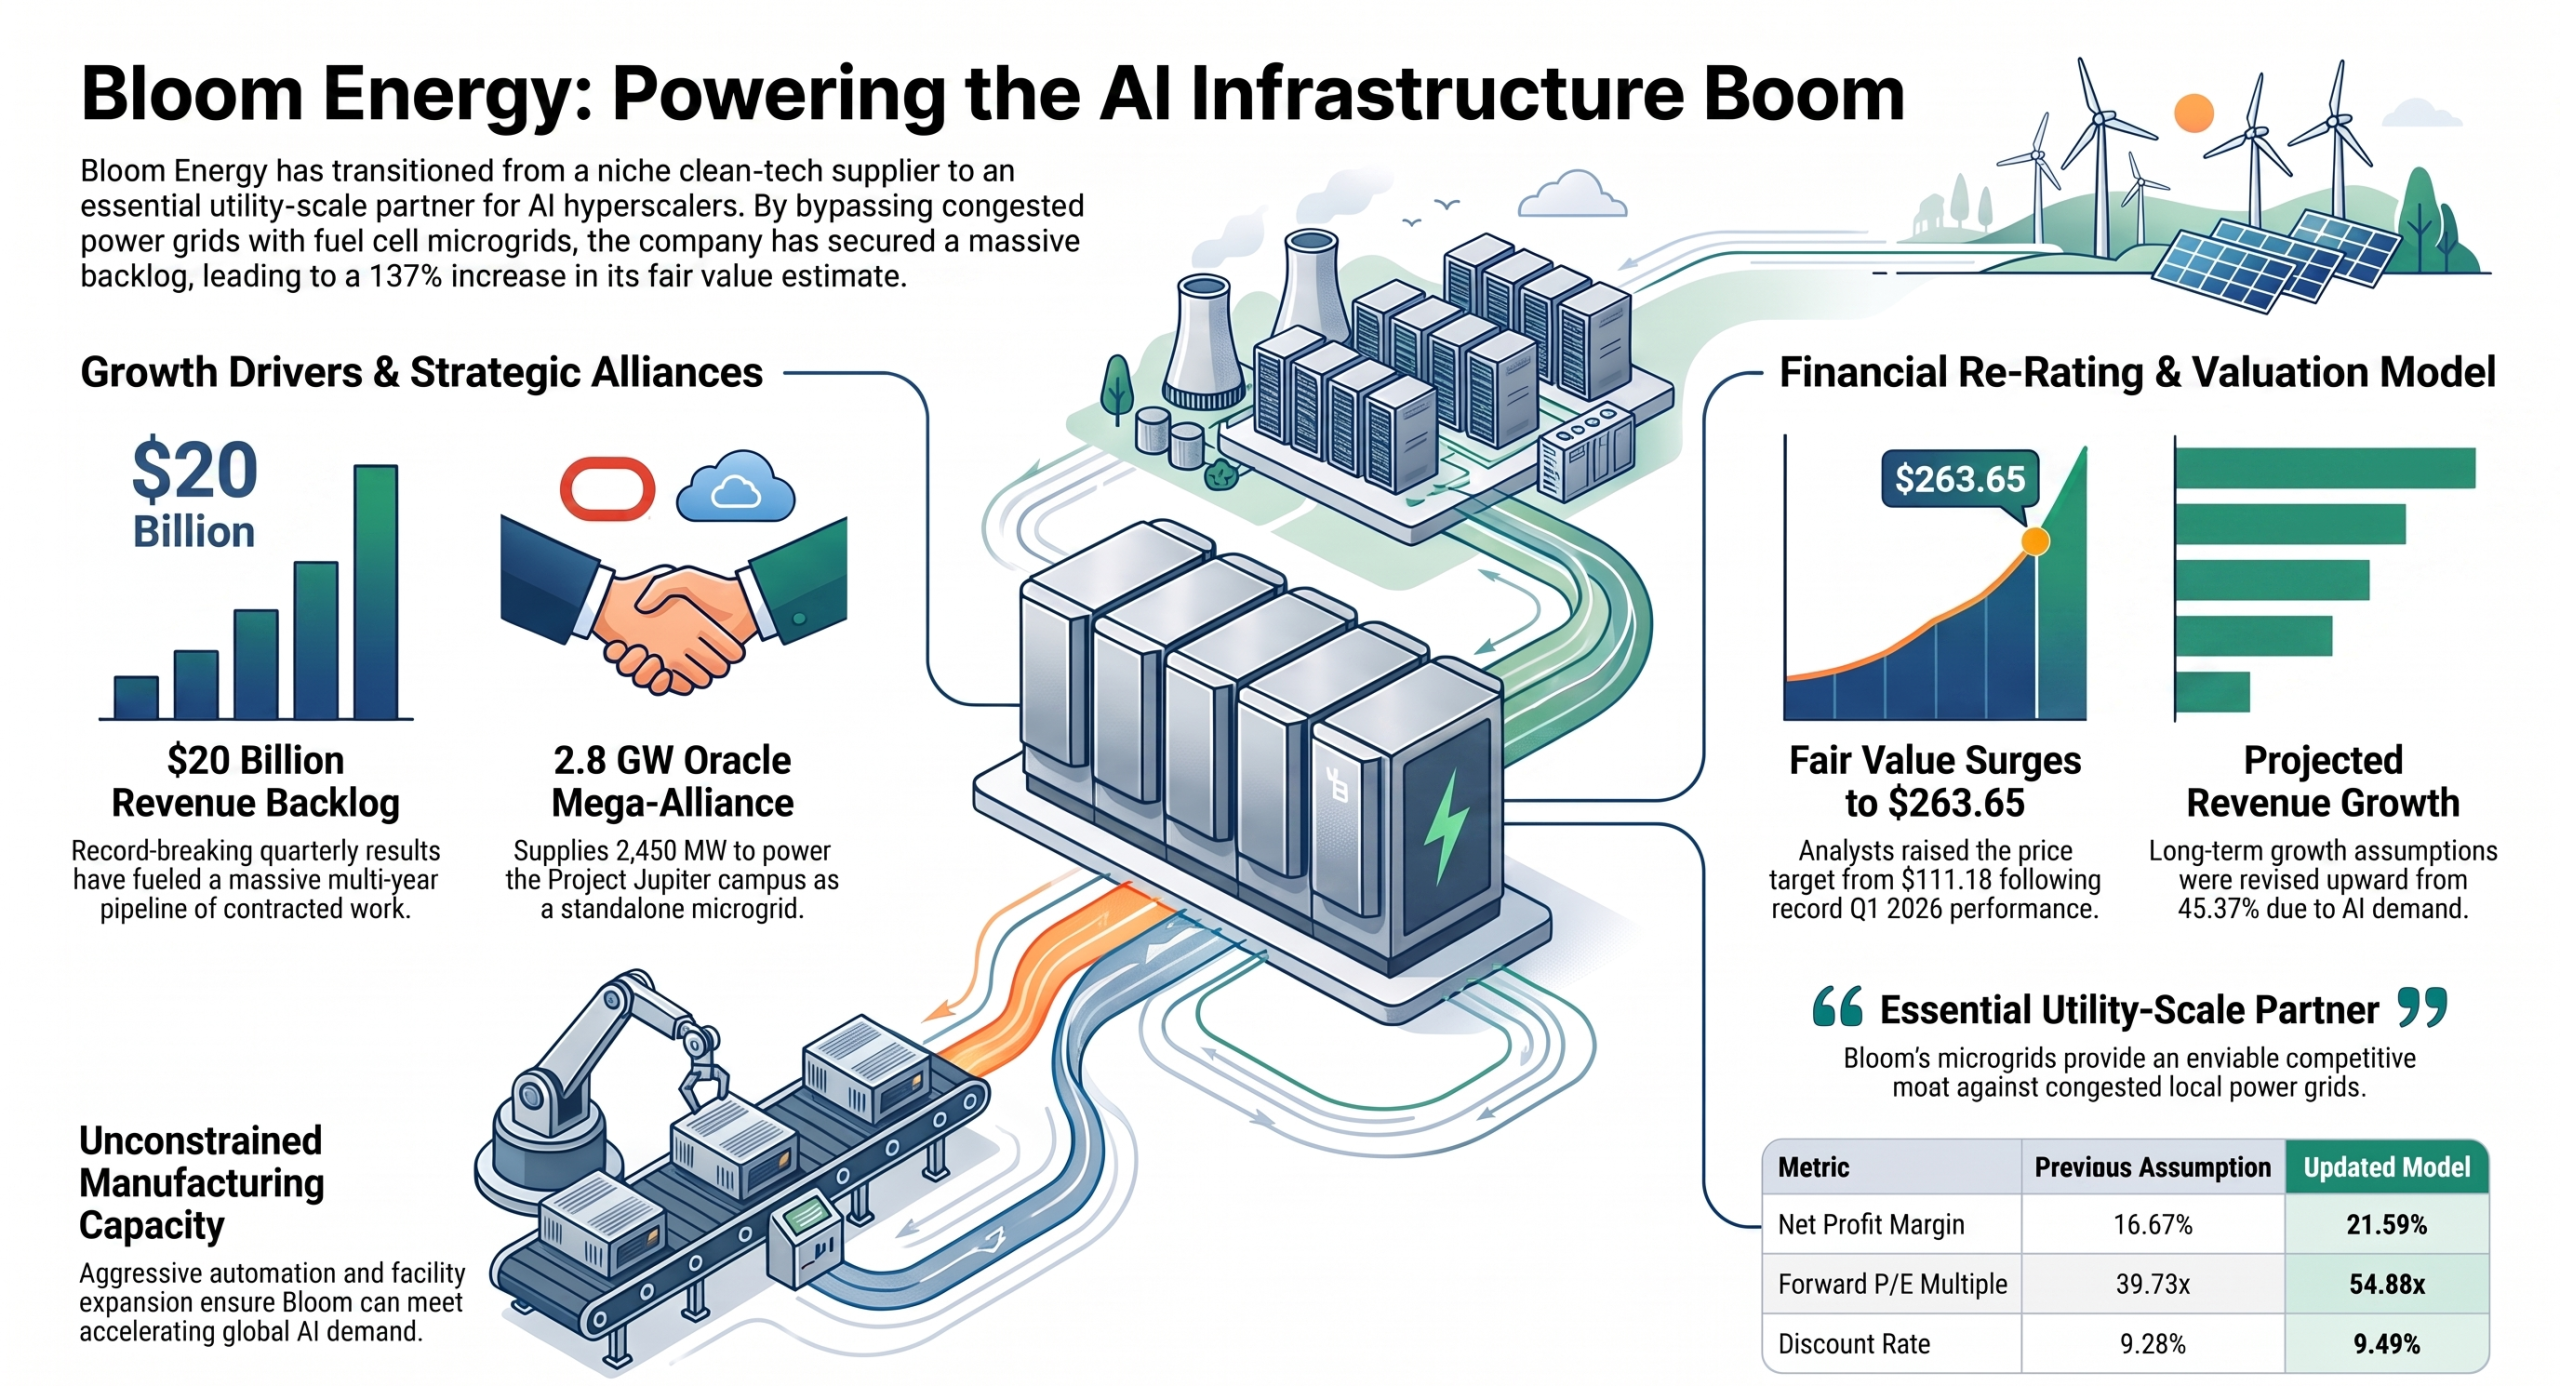
Bloom Energy is cementing its position as the premier off-grid power provider for the global AI infrastructure boom. As hyperscalers scramble for immediate, low-emission electricity, Bloom’s solid oxide fuel cells are stepping in to bypass traditional grid delays. Following record-breaking quarterly results and multi-billion-dollar contract wins, analysts have dramatically raised Bloom Energy’s fair value estimate from $111.18 to $263.65 per share.
Key Growth Drivers (Bull Case)
- Record Q1 2026 Results & Guidance Hike: Bloom reported Q1 revenue of $751 million, adjusted EPS of $0.44, and net income of $70.65 million (triggering a 23%+ stock surge). Backed by a massive $20 billion backlog, management raised full-year 2026 revenue guidance to $3.4 billion – $3.8 billion.
- The Oracle Mega-Alliance (Project Jupiter): Under an expanded master services agreement, Oracle intends to procure up to 2.8 GW of Bloom fuel cell systems. Crucially, this includes supplying up to 2,450 MW to fully power Oracle’s Project Jupiter AI data center campus in New Mexico as a standalone microgrid, completely replacing conventional gas turbines and diesel generators.
- $2.6 Billion Nebius Group Contract: Bloom signed a 10-year multi-phase deal with Nebius Group to power AI/cloud data centers across Europe and the U.S., starting with an initial 328 MW deployment this year. The focus on reduced water usage and lower emissions makes fuel cells an attractive alternative to legacy generation.
- Manufacturing Capacity Unconstrained: Management is aggressively expanding manufacturing capacity through automation and new facilities, confirming the business is not capacity-constrained to meet accelerating AI demand.
Risks to Monitor (Bear Case)
- Project Execution & Headline Volatility: The stock dropped over 10% following news of a temporary pause at a 1.8 GW Wyoming AI data center project (where Bloom was slated for 900 MW). While the utility indicated the project will proceed with a different development partner, it underscores how sensitive short-term sentiment is to project delays.
- Elevated Valuation Multiples: The updated analyst model embeds a significantly higher forward P/E multiple (54.88x, up from 39.73x), leaving less room for error if project rollouts or customer ramp-ups encounter friction.
Model & Valuation Changes at a Glance
| Metric | Previous Assumption | Updated Model |
| Fair Value Estimate | $111.18 | $263.65 |
| Long-Term Revenue Growth | 45.37% | 60.71% |
| Net Profit Margin | 16.67% | 21.59% |
| Forward P/E Multiple | 39.73x | 54.88x |
| Discount Rate | 9.28% | 9.49% |
Conclusion
Bloom Energy has transitioned from a niche clean-tech supplier to an essential utility-scale partner for the AI revolution. By providing multi-gigawatt microgrid solutions that operate independently of congested local power grids, BE possesses an enviable competitive moat. Despite short-term price volatility tied to individual site developments, the staggering $20 billion backlog and projected 60.7% revenue growth rate fundamentally justify its position as a high-conviction growth holding in our portfolio.
Source: Bloom Energy (BE) – Multi-Gigawatt AI Data Center Deals Trigger Massive Fair Value Re-Rating
